



 이미지 확대보기
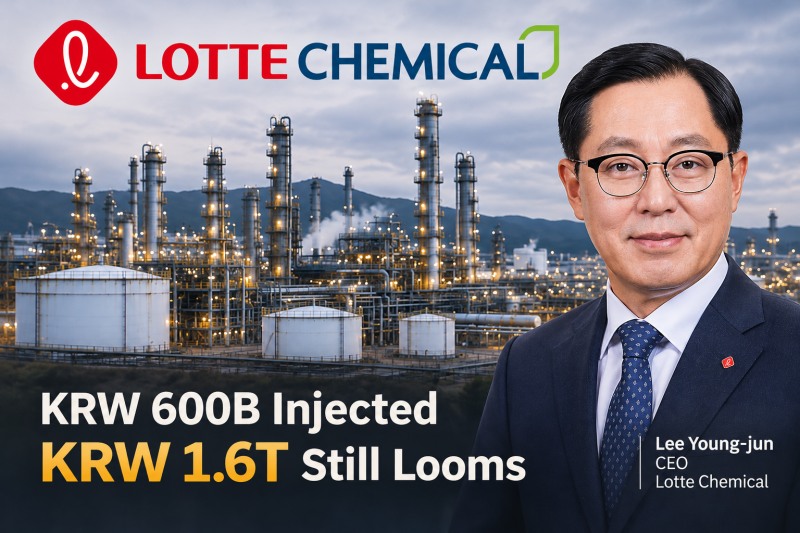
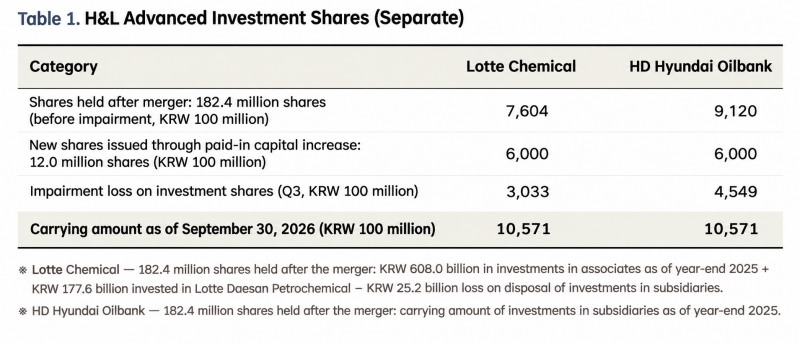
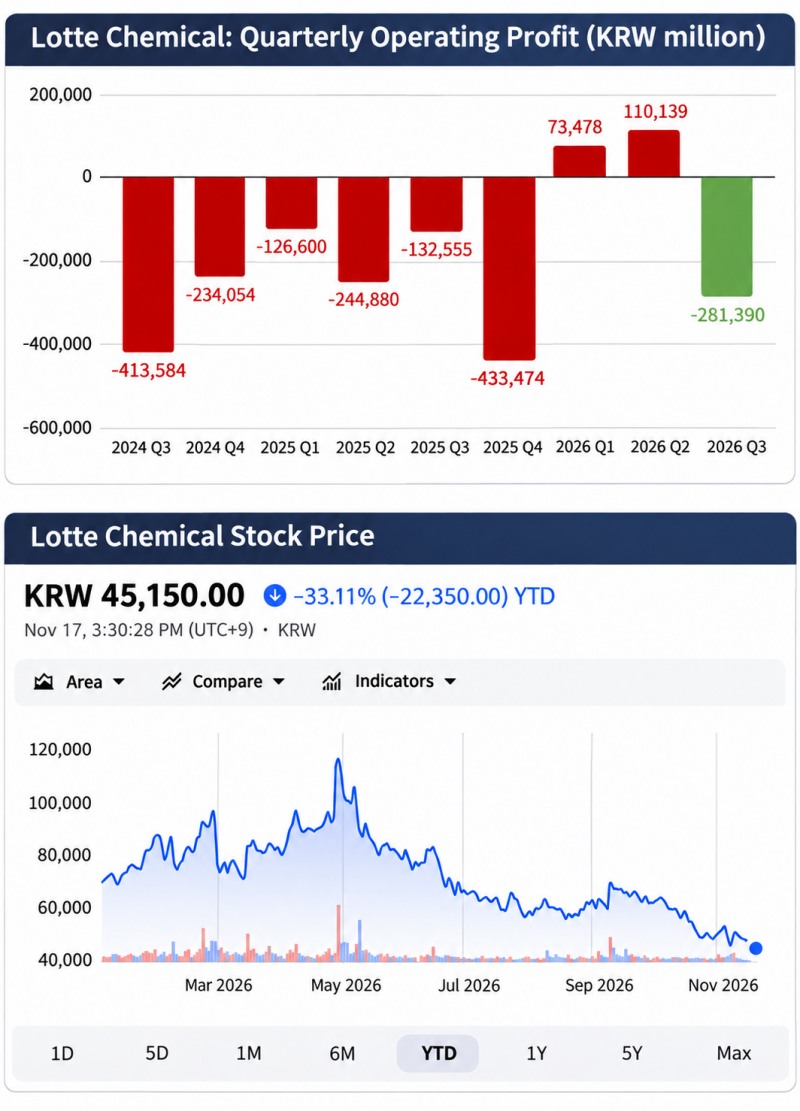
According to the Financial Supervisory Service’s electronic disclosure system on the 13th, Lotte Chemical recorded an impairment loss of KRW 303.3 billion on its investment in H&L Advanced in its third-quarter separate financial statements. HD Hyundai Oilbank, the other shareholder, also booked an impairment of KRW 454.9 billion. The combined impairment losses of the two companies come to KRW 758.2 billion.
Capital Goes to Debt Repayment, but KRW 1.6 Trillion Support Obligation Remains
H&L Advanced is a joint venture formed by the merger of Lotte Daesan Petrochemical, which Lotte Chemical created by spinning off its Daesan plant business, and HD Hyundai Chemical. The two companies signed the merger agreement in June and completed the merger in September. After the merger, Lotte Chemical received newly issued merger shares, raising its stake from 40% to 50%, while HD Hyundai Oilbank also holds a 50% stake.Despite the large capital injection, Lotte Chemical’s burden of additional support remains. According to the disclosure, the debt of H&L Advanced subject to funding support totals KRW 3.2484 trillion, and Lotte Chemical bears a funding support obligation of KRW 1.6242 trillion, equivalent to its 50% stake. This is KRW 567.1 billion more than the book value of its investment shares, KRW 1.0571 trillion, as of end-September.
A funding support agreement is an obligation separate from the book value of the investment shares, and the full amount does not immediately become actual repayment or a confirmed loss. Still, the fact that a substantial support burden for the JV’s borrowings remains even after the additional KRW 600 billion contribution is a financial burden factor for Lotte Chemical.
관련기사
Beyond "Future Businesses" to "One Lotte": Shin Yu-yeol's Succession Training Enters Act TwoLotte Chemical Returns to Profit, But Analysts Warn of Fifth Straight Annual LossA Shrimp Between Two Whales: Korea Petrochemical Caught Between S-Oil and ChinaGS Stock Hits Record High, Yet Still Trades at Half Its Book ValueLotte Chemical Swung to Profit in Q1 — So Why Won't the Stock Move?
Merger-date accounting value at 48% of prior valuation
The share value recognized in the merger process also stands out. When the merger ratio was set, the external valuation firm applied the discounted cash flow (DCF) method and assessed HD Hyundai Chemical’s per-share value at KRW 5,250. However, in the merger-date accounting, the H&L Advanced share value, reflecting the stake held by HD Hyundai Oilbank and the new merger shares received by Lotte Chemical, was about KRW 2,506 per share. That is about 48% of the earlier valuation.The gap between the two figures is notable given that less than three months separated the signing of the merger agreement and the merger date. That said, the external valuation used to set the merger ratio and the amount reflected in merger-date accounting differ in purpose and basis, so there are limits to a simple comparison.
 이미지 확대보기
According to industry sources, the valuation at the time of the merger took into account an outlook for an industry recovery in 2029, when the expansion of Chinese capacity is expected to ease. The creditors’ deferral period for covenant debt repayment was also set to March 2029. However, despite expectations of a longer-term industry recovery, current financial conditions remain challenging.
Lotte Chemical itself gets three-year deferral on covenant debt
Lotte Chemical itself is also receiving support from its creditors. At the end of the third quarter, the company signed a structural innovation support agreement with creditor financial institutions and obtained a deferral of repayment on its covenant debt for a three-year business restructuring period. Existing financial terms and the use of funds within existing limits will be maintained.The company also failed to meet its financial covenants on acquisition financing. For the KRW 690 billion in acquisition financing related to its purchase of Lotte Energy Materials, Lotte Chemical must keep its net financial debt-to-EBITDA ratio at or below 400% and its EBITDA-to-interest expense ratio at 5 times or higher. It disclosed that it met neither covenant at the end of the third quarter. Compliance with these covenants has been deferred until December 2027 with the consent of the lender group.
Lotte Chemical is thus tasked with restoring its business competitiveness and improving its financial structure during the three-year restructuring period. If it fails to deliver tangible results in that time, the burden of supporting H&L Advanced and the pressure to repay its own debt could combine to prolong its financial strain, some observers say.
 이미지 확대보기
Gwak Horyung (horr@fntimes.com)
데일리 금융경제뉴스 Copyright ⓒ 한국금융신문 & FNTIMES.com
저작권법에 의거 상업적 목적의 무단 전재, 복사, 배포 금지

가장 핫한 경제 소식! 한국금융신문의 ‘추천뉴스’를 받아보세요~