



 이미지 확대보기
Credit rating back in the A category after eight years
Korea Ratings raised Doosan Enerbility’s corporate bond rating by one notch, from BBB+ to A-, this past May, and NICE Investors Service did the same in June. The upgrade marks a return after about eight years since the company lost its ‘A-’ rating in 2018, when its financial burden grew and the government’s nuclear and coal phase-out policies took a toll.The rating subsequently fell to BBB in 2019 amid fallout from the troubles at Doosan Construction. In 2020, when the company entered creditor-led management over a liquidity crisis, it slid to BBB-, just above speculative grade.
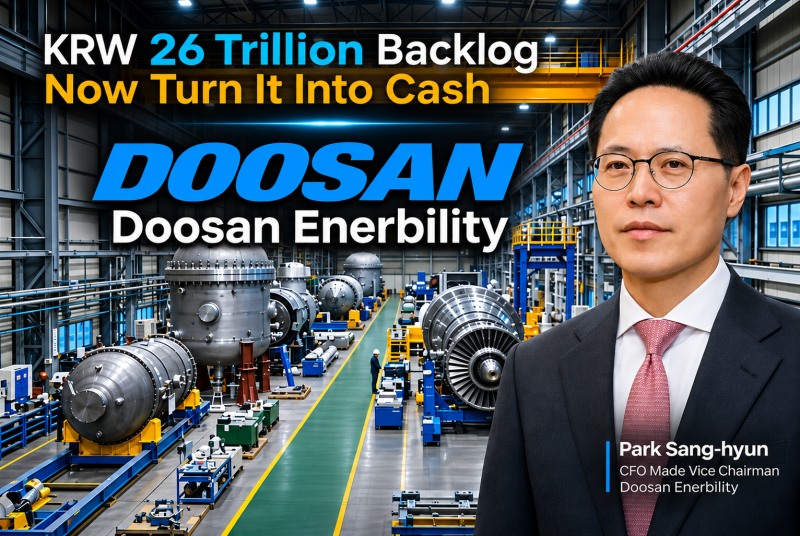
Park led this improvement in the company’s financial structure. Born in 1966, he graduated from Yonsei University with a degree in business administration and earned a master of business administration (MBA) from Duke University in the United States.
After joining Doosan Corp. in 2004 as a department head on the CFO team of its Strategic Planning Division, he held key posts across the group’s finance functions. He served as managing director of the CFP team in Doosan Corp.’s holding company division, head of financial management at Doosan Infracore, and executive vice president of Doosan Corp.’s holding company division, before becoming CEO of Doosan Bobcat in 2018.
관련기사
Small Reactors, Big Bets: Doosan Enerbility's SMR Revenue to Soar Nearly 10-FoldThe Robot Gamble: Doosan Robotics CEO Bets Big on North America Despite 11 Straight Years in the RedNearthLab: The Drone Startup That Inspected Wind Turbines — Now Targeting the Global Battlefield [Rising Stars of K-Defense]'From Heavy Industry to Humanoids' — Doosan Robotics Charts a New Future in Physical AI [K-Humanoid Wars, Part 3]Doosan Enerbility Eyes Return to 'A' Credit Rating After 9 Years on Nuclear Power and Gas Turbine Boom [KFT Topic]
Park is a financial expert with experience across the finances of the holding company and machinery and energy affiliates. He significantly reduced the company’s debt burden during his tenure. The ratio of net debt to earnings before interest, taxes, depreciation and amortization (EBITDA) fell from 13.0 times in 2021 to 4.1 times in 2023. This means the net debt burden relative to the profit generated from operations dropped to about one-third. Over the same period, gross borrowings declined from KRW 4.9074 trillion to KRW 3.2374 trillion.
From 2024, free cash flow remained in deficit as the working capital burden grew. Last year, the company kept its debt burden in check by selling its Vietnamese local subsidiary and recovering part of its loans to affiliates. Net debt/EBITDA improved from 5.6 times in 2024 to 4.6 times last year, and reliance on borrowings eased from 26.8% to 25.5%.
Short-term solvency also improved. The current ratio (consolidated basis), which divides assets convertible to cash within a year by liabilities due within a year, stood at 76% at the end of 2020, when Park joined. It surpassed 100% at the end of 2022 and rose to 112.3% at the end of 2024.
The reshuffle also reorganizes Doosan Enerbility’s management lineup. Song Yong-jin, president and head of the Strategy and Innovation Division, who has an engineering background, was appointed the new chief operating officer (COO). Song will lead efforts to strengthen competitiveness in businesses such as nuclear power, gas turbines and offshore wind, while Park will handle the financial strategy to support those efforts.
Test of turning the order boom into cash
Park’s first task as vice chairman is to convert the growing workload into cash. The order backlog of Doosan Enerbility’s Enerbility segment rose to KRW 26.3509 trillion as of the end of June this year. Orders for gas turbines and small modular reactors (SMRs) have grown rapidly on the back of rising power demand from AI data centers.The problem is that orders do not immediately translate into cash inflows. Large power generation equipment takes a long time to manufacture, creating a time lag between construction progress and payment collection. When collection of project payments is delayed or inventories increase, cash gets tied up in operations and the working capital burden grows.
Indeed, consolidated cash flow from operating activities plunged from KRW 2.0706 trillion in 2023 to KRW 242.2 billion in 2024. It recovered to KRW 751.8 billion last year, but in the first half of this year there was a net outflow of KRW 886.7 billion, a wider outflow than the KRW 584.8 billion net outflow a year earlier. On a standalone basis, excluding subsidiaries such as Doosan Bobcat, the company recorded net outflows for two consecutive years, KRW 113.7 billion in 2024 and KRW 151.7 billion last year.
This reflected a combination of factors: the delayed change contract and receivables collection on the Turkistan combined-cycle power plant project in Kazakhstan, payments to secure gas turbine production slots, and advance manufacturing of gas turbines for North America.
Working capital demands combined with capital expenditure pushed borrowings higher. Short-term borrowings due within a year exceeded KRW 4 trillion at the end of the second quarter. Over the same period, cash and cash equivalents fell from KRW 3.081 trillion at the end of last year to KRW 2.5419 trillion at the end of June, and the current ratio dropped to 103.3%.
The debt burden that had been lowered through last year has risen again this year. Standalone gross borrowings increased from KRW 3.7923 trillion at the end of last year to KRW 4.429 trillion at the end of March this year. On an annualized first-quarter basis, the ratio of gross borrowings to EBITDA was 8.4 times and the net debt ratio was 7.3 times, both higher than the 5.8 times and 4.6 times at the end of last year.
Still, the debt burden is assessed as manageable, given that collection of major receivables is scheduled for the second half and earnings power is improving.
Doosan Enerbility plans to proceed with investment in a new SMR plant flexibly, in line with the level of orders secured. In the medium to long term, it aims to expand equipment sales centered on large nuclear reactors, SMRs and gas turbines. The equipment business has a shorter project execution period than the engineering, procurement and construction (EPC) business, so its cash collection cycle is also relatively short. Payments for major delayed projects are expected to come in gradually starting in the second half of this year.
Ultimately, Park’s task is to prove again the financial management capability that brought a leverage multiple of 13 times, seen during creditor-led management, down to the 4-times range. He must collect delayed project receivables on time and absorb growing investment demand while maintaining an A-grade credit rating.
Jung Jina (urzinnie@fntimes.com)
데일리 금융경제뉴스 Copyright ⓒ 한국금융신문 & FNTIMES.com
저작권법에 의거 상업적 목적의 무단 전재, 복사, 배포 금지

가장 핫한 경제 소식! 한국금융신문의 ‘추천뉴스’를 받아보세요~