



 이미지 확대보기
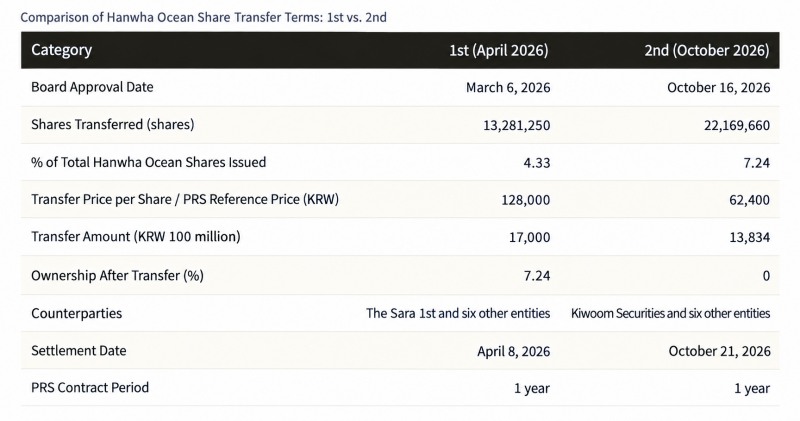
According to the investment banking (IB) industry on Oct. 20, Hanwha Systems recently decided to transfer all 22,169,660 of its Hanwha Ocean common shares to Kiwoom Securities and six other parties through an after-hours block trade. The transfer price is KRW 62,400 per share, for a total of KRW 1.3834 trillion.
This is not a simple sale but a PRS. Under a PRS, gains from a rise in the share price and losses from a fall accrue to the issuer.
Notably, each PRS contract has a term of one year. Because three-year contracts are typical, the short term is one factor that raises the likelihood that Hanwha Systems will ultimately dispose of its Hanwha Ocean stake.
 이미지 확대보기
Hanwha Systems Unwinds ‘Bridge’ Role in Hanwha Ocean Acquisition
관련기사
Hanwha’s Three Defense Units Split Roles After Reshuffle: Localization, Space·AI and North AmericaIn the Black, Short on Cash: Hanwha Solutions Injects KRW 400 Billion into Its U.S. Solar UnitHanwha Robotics Gets KRW 23 Billion Lifeline as Kim Dong-seon Doubles DownHanwha Aerospace's New Playbook: Pairing Weapons Deals with Energy SupplyLIG D&A, Hanwha Systems Enter Full-Scale Rivalry as Defense AI Battle Reaches the Boardroom
Even so, given the background of how Hanwha Systems acquired its Hanwha Ocean stake and the current situation, observers see this as a strategy with an eventual sale in mind.
When the Hanwha Group acquired Hanwha Ocean (then Daewoo Shipbuilding & Marine Engineering) in 2022, major affiliates including Hanwha Aerospace, Hanwha Systems and Hanwha Impact shared the investment. There were considerable concerns that a single company shouldering the roughly KRW 2 trillion in funding would suffer a deterioration in its credit rating and financial soundness.
Hanwha Systems therefore served as a kind of “bridge” in the group’s push to strengthen its strategic businesses. In particular, Hanwha Systems effectively monopolizes the domestic naval combat management system (CMS) market, so joining the consortium helped solidify the rationale for the group’s strengthening of its defense business.
Tighter Working Capital Management… Free Cash Flow Also Gradually Shrinking
In the defense industry, actual cash flow can worsen even as the order backlog grows, because capital expenditure (CAPEX) and various costs are incurred first and payment is collected later.
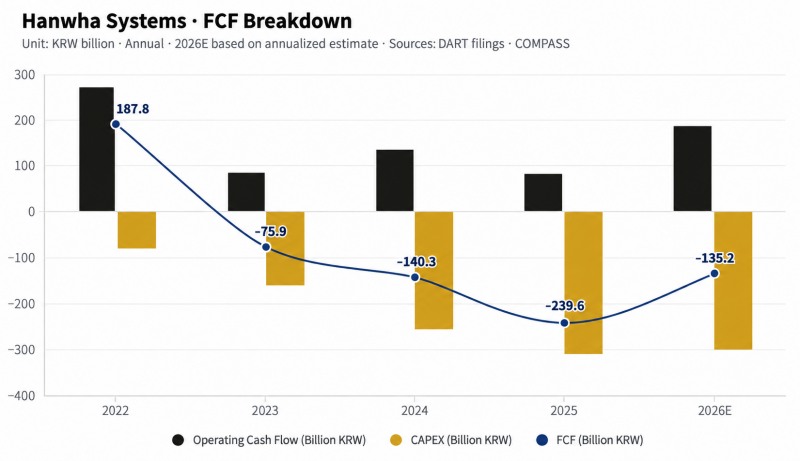
In fact, although Hanwha Systems’ revenue and earnings are on an upward trend, its free cash flow (FCF) has remained negative. As current liabilities have exceeded current assets, managing short-term liquidity and working capital has become even more important.
 이미지 확대보기
The PRS issuance fills this funding gap, and the sale of the Philly shipyard stake (a 60% stake, about KRW 325 billion) serves the same purpose. The funds raised through the PRS and the shipyard sale come to approximately KRW 3.4 trillion.
Hanwha Systems plans to invest the proceeds in its space, defense and artificial intelligence (AI) businesses. It is ending its bridge role in the group’s business restructuring and focusing on future businesses.
Because of the PRS contracts, gains and losses from changes in the value of the Hanwha Ocean shares still remain with Hanwha Systems. If the share price falls further, the amount Hanwha Systems has to pay will also increase.
Hanwha Systems’ average acquisition cost for its Hanwha Ocean stake, obtained through the acquisition and subsequent participation in capital increases, is about KRW 18,000 per share. At the start of this year, Hanwha Ocean’s share price even exceeded KRW 150,000. It has since fallen to about KRW 60,000, but that is still more than three times the amount Hanwha Systems invested. It is too early to call it an “investment loss,” as the cushion remains large.
Meanwhile, although Hanwha Systems successfully completed the Hanwha Ocean acquisition, the rise in the stake’s value has left its capital allocation efficiency extremely low. It is now time to focus more on improving the latter through asset reallocation. The PRS issuance can be seen as an extension of that effort.
An IB official said, “As Hanwha Ocean’s share price has fallen sharply, the market tends to focus on concerns about Hanwha Systems’ PRS settlement. But it overlooks the fact that, while Hanwha Systems enjoys enormous valuation gains, its capital utilization efficiency is declining because the stake has grown so large.” He stressed, “From the Hanwha Ocean acquisition until now, Hanwha Systems has successfully fulfilled the position assigned to it.”
Lee Sungkyu (lsk0603@fntimes.com)
데일리 금융경제뉴스 Copyright ⓒ 한국금융신문 & FNTIMES.com
저작권법에 의거 상업적 목적의 무단 전재, 복사, 배포 금지

가장 핫한 경제 소식! 한국금융신문의 ‘추천뉴스’를 받아보세요~