

 이미지 확대보기
However, with return on invested capital (ROIC) stuck in the 5% range and the cost of invested capital rising every year, the company’s economic value added (EVA) deficit continues to widen.
To improve investment efficiency, Hyundai Mobis is slimming down invested capital and reallocating capital, including by selling low-margin businesses. To enter a phase of genuine value creation, it needs visibility on a medium- to long-term turnaround in robotics, electrification and other areas. The problem is that the timing remains uncertain.
ROIC Stuck Near 5% as Capital Cost Burden Grows
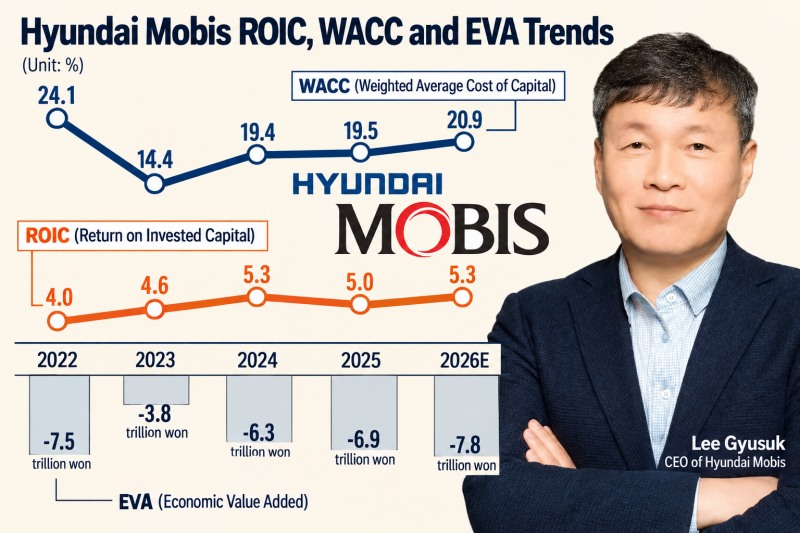
According to THE COMPASS, an AI-powered corporate analysis platform built by Korea Financial Times, Hyundai Mobis’s ROIC was 4.01% in 2022, 4.61% in 2023, 5.28% in 2024 and 5.02% in 2025, moving within a 4–5% range. The forecast for this year is 5.25%, a slight increase.ROIC is the ratio of net operating profit after tax (NOPAT) generated by the capital invested in operations (invested capital, or IC), and is a key measure of capital efficiency. The lower the figure, the less efficient the investment.
At Hyundai Mobis, investment in robotics, semiconductors and battery in-sourcing enlarges invested capital, so NOPAT must rise at the same time for ROIC to improve. The problem is that, at this stage, revenue leverage is not keeping pace with the scale of investment.
Consider the company’s results over the past five years. Revenue has expanded steadily, from KRW 51.0963 trillion in 2022 to KRW 59.2544 trillion in 2023, KRW 57.2593 trillion in 2024, KRW 60.0824 trillion in 2025 and KRW 63.8 trillion in 2026 (estimate).
Operating profit, however, stood at KRW 2.0265 trillion in 2022, KRW 2.2953 trillion in 2023, KRW 2.5221 trillion in 2024, KRW 2.846 trillion in 2025 and KRW 3.2 trillion in 2026 (estimate). The operating margin rose only from 3.9% in 2022 to about 5.02% in 2026 (estimate), so the company has yet to escape a low-margin structure of 3–5%.
Returns are stagnant, but capital expenditure (CAPEX) is trending upward. Hyundai Mobis’s CAPEX was KRW 1.2 trillion in 2022, KRW 1.9 trillion in 2023 and KRW 2.4 trillion in 2024, rising by more than operating profit did. It fell back to around KRW 1.5 trillion in 2025, but very little of the CAPEX that peaked in 2024 has translated into profit.
THE COMPASS’s analysis of Hyundai Mobis’s 2025 ROIC structure shows a NOPAT margin of 4.09% and a capital turnover ratio of 1.28x. In the low-margin auto parts industry, a 1.28x turnover is not unreasonable. But the structural inefficiency remains unresolved: ROIC, the product of the two factors, falls far short of the cost of capital.
EVA Trapped by Investment Efficiency
Hyundai Mobis’s investment inefficiency also shows up in its weighted average cost of capital (WACC). WACC is the cost of financing, calculated as the weighted average of the cost of equity and the cost of debt (borrowings) within the capital invested. It serves as the profitability benchmark against which ROIC is compared.Hyundai Mobis’s WACC fell from 24.05% in 2022 to 14.45% in 2023, then rose again to 19.42% in 2024, 19.48% in 2025 and 20.92% in 2026 (estimate).
Within the WACC, the cost of debt is very low at 0.83%. With leverage of only 0.07x and debt accounting for about 31.5% of capital, borrowing costs themselves are not a burden on management. The problem is the cost of equity, which accounts for the remaining 68.5%.
The cost of equity is the annual growth rate a company would need to achieve to justify its current market capitalization, worked out in reverse. It represents the implied growth expectation (shareholders’ required return) the market assigns to the company. The higher the figure, the greater the market’s expectations, and failing to meet them puts downward pressure on the share price.
The cost of equity that shareholders (the market) require of Hyundai Mobis is 30.26%, which fell from 35.1% in 2022 before rising again. This suggests the market is attaching a considerable premium to Hyundai Mobis’s investment performance. With a capital structure that relies little on debt, a high cost of equity has become entrenched as the factor pulling up the overall WACC.
In short, shareholders and investors have high hopes for investment aimed at transforming the company’s fundamentals through robotics, semiconductors and battery in-sourcing, but the company has yet to turn those hopes into results.
The indicator that reveals this situation is the ROIC–WACC spread. A positive spread means ROIC exceeds the weighted average cost of capital and the company is creating value. A negative spread means returns fall short of the cost of capital and value is being destroyed, indicating a need for structural improvement.
Hyundai Mobis’s ROIC–WACC spread was –20.04% in 2022, –9.84% in 2023, –14.14% in 2024, –14.46% in 2025 and –15.67% in 2026 (estimate). The improvement seen temporarily in 2023 has since reversed.
EVA, which represents a company’s economic value added, is estimated at –KRW 7.8 trillion on an annualized basis from cumulative results through the second quarter of 2026. That is more than double the deficit of –KRW 3.8 trillion in 2023.
When Will the New Businesses Deliver?
The conditions for a Hyundai Mobis turnaround are clear. For ROIC to converge toward WACC, either the current ROIC of about 5.25% must rise meaningfully, or the cost of equity the market requires (30.26%) must come down.The path to improving ROIC that Hyundai Mobis is now pursuing is for sales of high-margin semiconductor and electronic components, such as BMICs, to take off once in-sourcing is complete, while capital turnover improves at the same time through capital reallocation.
For now, Hyundai Mobis is selling low-margin businesses to secure liquidity and improve efficiency.
The definitive agreement for the sale of its lamp business, disclosed on September 30, is interpreted as a sweeping restructuring to shed a representative low-margin legacy component and slim down invested capital, timed with its shift to focus on technology.
The cash and capital coming in from the sale of low-margin businesses will be used to secure liquidity and to concentrate R&D resources on semiconductors and electrification. This could act as a practical catalyst for narrowing the ROIC–WACC spread.
Automotive semiconductors and battery in-sourcing, which the company has made strategic high-margin businesses alongside robotics, are also gaining momentum. Hyundai Mobis’s BSA business entered full-scale mass production and supply in the second half of this year, when the build-out of its production bases in North America (including Georgia) and its joint-venture plant in Indonesia was completed. In semiconductors, the company is running a roadmap to apply next-generation SiC (silicon carbide) power semiconductors and its proprietary BMIC chips in phases across the electrification and SDV (software-defined vehicle) platforms of the group’s automakers by 2030.
“If Hyundai Mobis fully installs its proprietary BMICs and SiC power semiconductors in hybrid and EREV (extended-range electric vehicle) systems, where demand is high, and monetizes low-margin businesses in parallel, the pace of the ROIC rebound could accelerate through a higher NOPAT margin,” said an official at a securities firm.
Kim JaeHun (rlqm93@fntimes.com)
데일리 금융경제뉴스 Copyright ⓒ 한국금융신문 & FNTIMES.com
저작권법에 의거 상업적 목적의 무단 전재, 복사, 배포 금지

가장 핫한 경제 소식! 한국금융신문의 ‘추천뉴스’를 받아보세요~